Debt Payoff Calculator
Put in each balance, rate and minimum, choose a method, and see the debt-free month, the total interest, and which debt goes first.
| Debt | Balance | APR % | Minimum / mo |
|---|
| # | Debt | Balance | APR | Paid off |
|---|
Interest compounds monthly at APR ÷ 12 on the remaining balance; minimums stay fixed and roll onto the next debt when one is paid off. Runs in your browser; nothing is sent or saved.
How to use it
Pick a method and a number
-
List every debt
Balance, APR and minimum payment from each statement. Cards, car loans, student loans, personal loans, medical bills on a plan: all of them.
-
Add your extra
The amount above the minimums you can send every month. Even 50 dollars changes the date, and the tool shows how much interest it saves.
-
Compare the methods
Avalanche attacks the highest rate first and costs the least. Snowball clears the smallest balance first and gives you a win sooner. Pick the one you will stick with.
Keep it going every month
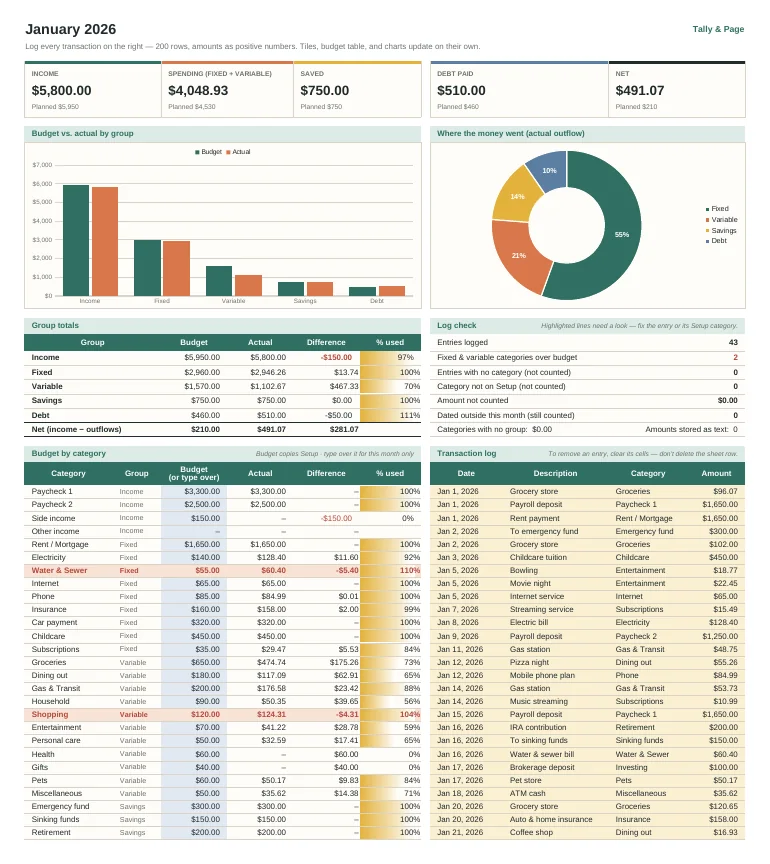
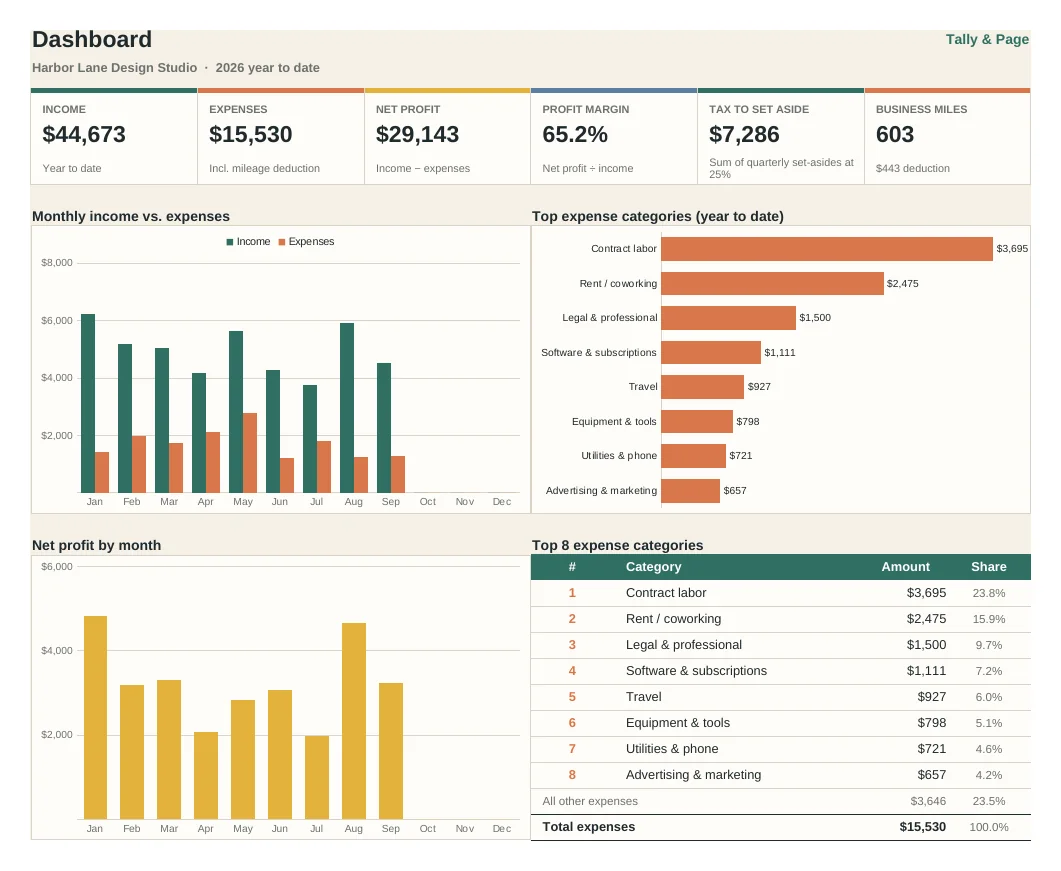
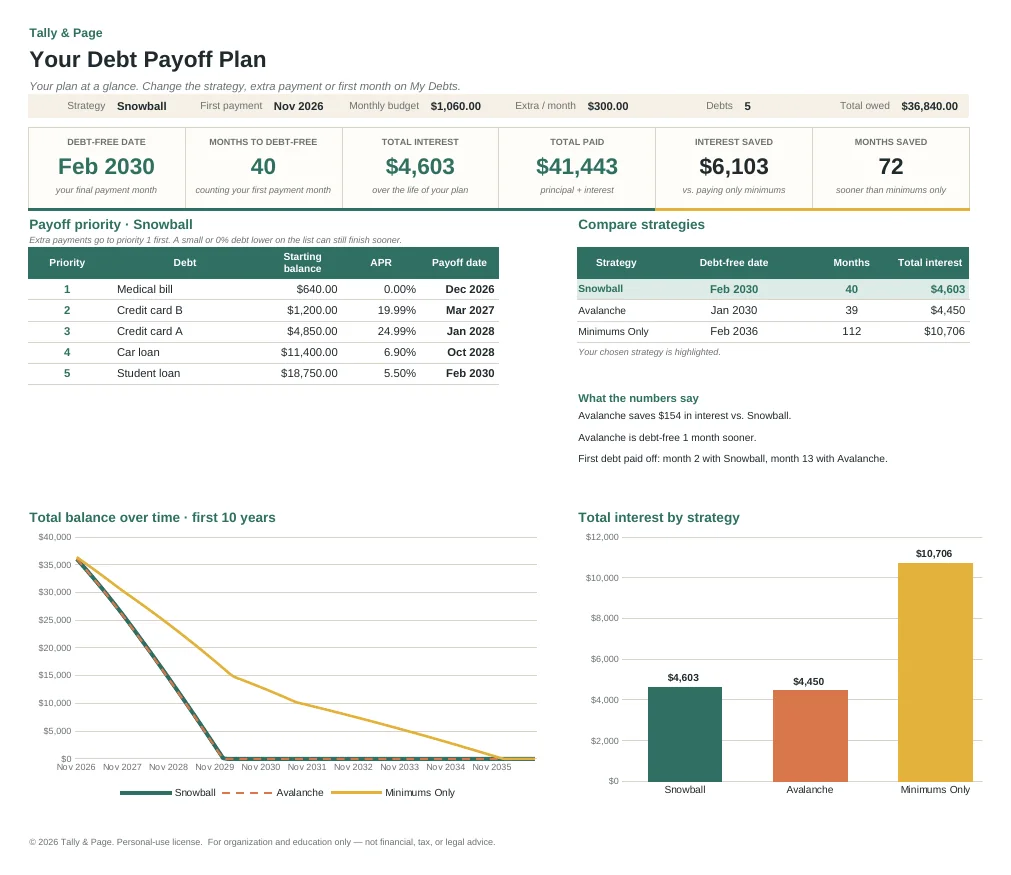
Debt Payoff Planner Spreadsheet
Your debt-free date, worked out to the month, with the interest you save.
- Plan up to 10 debts: cards, car, student, medical, and personal loans
- Compare snowball and avalanche side by side, against paying minimums only
- Debt-free date, months to go, total interest, and total paid at a glance
- Interest and months saved versus paying only the minimums
- Freed-up minimum payments roll into the next debt automatically
Or get it in the Money & Business Planning Bundle with the other templates, for $39.
Questions
Good to know
Which method is better?
Avalanche costs less in interest. Snowball pays off a whole account sooner, which keeps many people going. If the interest difference is small, choose snowball; if it is large, avalanche.
Why does the date not move when I add a debt?
Each new debt adds its own minimum, so the extra is spread thinner. Check that the APR is a yearly percentage, not a monthly one.
What does the tool assume?
Interest compounds monthly on the remaining balance, minimums stay fixed, and when a debt is paid off its minimum rolls onto the next one. It does not model fees or rate changes.
More free tools
Try another one
More templates